

Some observers may label the 2025 Atlantic hurricane season as a “quiet” year due to zero U.S. hurricane landfalls, but from an insurance and catastrophe risk perspective, that conclusion misses the point—and, potentially, the risk.
Executive Summary
The 2025 Atlantic hurricane season produced no U.S. Atlantic hurricane landfalls—but that outcome masks important lessons for insurers.Here, Verisk meteorology and scientific risk modeling experts Tory Farney and Wesley Terwey unpack why storm counts, landfalls and insured losses often diverge, and what last year’s season can reveal about hurricane risk heading into the 2026 season. Drawing on catastrophe modeling insights and historical context, they explain why so-called “quiet” seasons can be misleading—and why preparedness matters even when forecasts call for lower activity.
By the numbers, 2025 finished close to average. The Atlantic basin produced 13 named storms, five hurricanes and four major hurricanes, aligning closely with long‑term averages for total activity. What set the season apart was where storms went, not how many formed. For the first time since 2015, no hurricanes made U.S. landfall, even as powerful storms tracked across the broader Atlantic and Caribbean.
It’s often overlooked that three storms reached Category 5 intensity in 2025, a tally second only to the 2005 season. In other words, the season generated extreme risk signals, even though those storms never intersected with major U.S. exposures.
That distinction matters for insurers, particularly when interpreting seasonal outlooks, claims experience and forward-looking risk.
Basin Activity Doesn’t Equal Landfall Risk
Major hurricanes are typically the storms with the greatest loss potential. In 2025, the basin generated disproportionately intense storms relative to total counts, signaling a risk environment that was more elevated than insured losses alone might suggest.
Seasonal hurricane forecasts are designed to estimate basin-wide activity, not pinpoint impacts. They can offer guidance on how many storms might form, how intense they could become, and how much overall energy the season may generate. What they cannot do months in advance is predict if and where storms will ultimately make landfall.
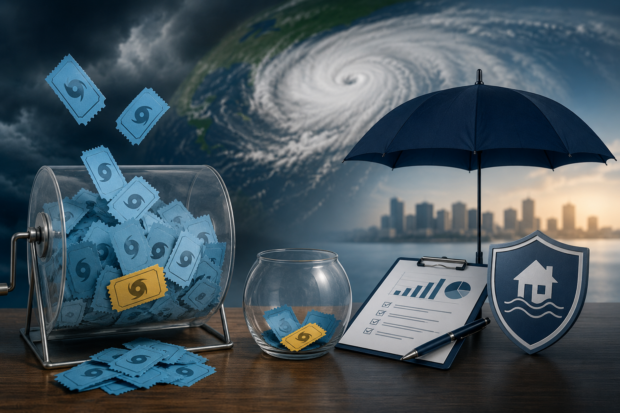
A helpful way to think about seasonal forecasting is a raffle analogy. A more active season effectively prints more raffle tickets, increasing the odds of hitting one. But having more tickets doesn’t guarantee a winning number, and fewer tickets doesn’t eliminate the chance of one being drawn.
More tickets raise the odds, not the outcome.
For insurers, that distinction matters because preparation and pricing decisions are largely influenced by expected impact, not basin-wide activity alone.
Why 2025’s Tracks Mattered More Than Its Totals
Large‑scale climate signals help explain why 2025 unfolded the way it did. For much of the season, the tropical Pacific hovered in a weak La Niña‑like state, while Atlantic sea surface temperatures remained above average. That combination typically favors storm formation and intensification, which is exactly what the basin saw.
Other climatological and large-scale factors, though, did not favor U.S. landfalls.
Persistent troughs and low‑pressure systems over the western Atlantic and eastern U.S. helped steer storms northward and out to sea before they could reach the coast. Storm formation also skewed heavily toward the central and eastern Atlantic, while the Gulf of Mexico and the Caribbean Sea were comparatively quiet in terms of genesis.
Storm‑to‑storm interactions also played a role. In one case, Hurricane Humberto likely altered the path of nearby Hurricane Imelda, potentially preventing what could have been a low‑end U.S. hurricane landfall, a reminder that outcomes can hinge on dynamics no seasonal forecast can anticipate.
Only one storm made landfall in the U.S. during the season: Tropical Storm Chantal, which hit South Carolina, producing inland flooding and isolated wind damage.
After nine consecutive years of U.S. hurricane landfalls, 2025 ended the streak. However, this is not an uncommon occurrence in the Atlantic since, historically, the two most common outcomes for U.S. hurricane landfalls in a year are one and zero, with the latter occurring in about 20% of all years.
Losses Didn’t Disappear—They Shifted
From a claims perspective, according to Verisk, the absence of U.S. hurricane landfalls in 2025 resulted in significant decline in hurricane-driven losses compared with the previous year. But catastrophe risk didn’t decline.
For insurers with exposure beyond the continental U.S., 2025 told a very different story, as Hurricane Melissa caused severe damage and devastation in Jamaica and parts of the Caribbean.
Within the U.S., hurricane activity is only one component of the catastrophe risk landscape. Severe convective storms, winter weather and other nontropical perils continue to shape claims outcomes year after year, even when hurricane tracks “cooperate.”
For claims and CAT teams, that shift reinforces why resource planning can’t be optimized around last season’s experience alone.
Looking Ahead: Competing Signals and Continued Uncertainty
Early preseason forecasts from various sources, such as the one released by Colorado State University, suggest that the upcoming 2026 Atlantic hurricane season’s activity is likely to be slightly below average, driven by a likely El Niño pattern that tends to suppress overall activity in the basin. At the same time, Atlantic sea surface temperatures remain warmer than historical norms, creating competing signals that add uncertainty to seasonal outlooks.
History offers a clear caution: even lower‑activity seasons can produce high-impact outcomes. Seasonal forecasts should provide perspective, not reassurance.
Bringing Physical Realism Into the Next Generation of U.S. Hurricane Risk Models
As the industry continues to learn from each hurricane season, such as 2025, catastrophe models are evolving alongside it. Verisk’s soon to be released update to its Tropical Cyclone Model for the U.S., which will be live in June 2026, reflects that evolution across every model component.
The evolution of U.S. tropical cyclone models reflects a broader rethinking of how physical processes are represented. Rather than computing winds at gradient level and translating them to the surface, the updated tropical cyclone model simulates surface winds directly, expressed as 3-second gusts to better reflect how damaging conditions occur. Wind-field asymmetries, previously tied to a storm’s forward speed, are now linked to the broader environmental state the storm moves through. These refinements matter especially for storms affecting the Northeast and those undergoing extratropical transition, where asymmetric footprints have historically been difficult to replicate.
The updated tropical cyclone model also introduces a single near-present climate catalog conditioned on current sea surface temperature and ENSO states, replacing a prior binary catalog approach. That shift affects not just how many storms are simulated but how intensity distributions and landfall probabilities vary by region.
At the same time, advances in vulnerability modeling, including explicit treatment of roof age, rebuilding cycles following recent storms and county-level variation in building code enforcement, help align modeled losses more closely with today’s exposure. Together, these changes are designed to deliver a more transparent, defensible view of risk that better supports underwriting, reinsurance and capital decisions.
The Bottom Line
The 2025 hurricane season was neither a fluke nor a free pass. It showed how favorable steering patterns can temporarily limit impacts while underlying risk remains elevated.
For insurers and claims professionals, the takeaway is that last season’s landfalls alone may not fully reflect underlying risk. Risk can instead be assessed based on exposure, preparedness and the understanding that hurricane risk isn’t revealed by the absence of landfalls—it’s revealed by how alignment, timing and exposure eventually intersect.
Seasons like 2025 don’t indicate reduced risk; they underscore how much hurricane loss ultimately depends on where—and when—storms meet exposure.
 Viewpoint: The One Thing Holding Back Insurers’ AI Efforts
 Levers and Guardrails: How Growth Is Being Built at Hippo
 Insurance AI’s Next Test: Can Carriers Trust the Data?
 Viewpoint: Pricing Wildfire Risk Is Not the Same as Reducing It