

Back in 2015, after working more than 15 years on the underwriting side of the property/casualty insurance business, Chad Nitschke started to become frustrated with the lack of change in the industry.
Executive Summary
Vouch, an InsurTech that underwrites commercial and management liability insurance for high-growth technology and life science startups, is the brainchild of Sam Hodges and Travis Hedge. Here, the co-founders describe past experiences with entrepreneurship and startup investing that fueled a mission to correct the problems of time-consuming underwriting processes and ill-fitting coverage for their target customers, along with recent milestones and possibilities for the future as industry veteran Chad Nitschke takes the reins of a new division—Vouch Specialty.“I just felt like the rest of the world was evolving, but the insurance industry wasn’t really keeping pace with a lot of the other industries,” said Nitschke, president of Vouch Specialty, recalling his feelings at the time.
Before taking his role at a new division of InsurTech Vouch earlier this year, Nitschke made an initial leap to the world of faster-paced companies that started to pop up in the insurance sector five years ago. Switching gears from being an underwriter of specialty lines like D&O and professional liability, and from being an executive who managed niches like credit union protection and small business commercial business at the likes of Travelers, CUNA Mutual and AXIS Capital, he co-founded InsurTech Bunker, a startup focused on independent contractors and small businesses, in March 2016.
Describing the uneasiness that first pushed him toward the InsurTech world, Nitschke said he felt that new product development in the traditional industry wasn’t really in tune with customer problems. He recalled one insurance executive at an incumbent telling him, “We have all of these bad customers…People that call in, and they have a policy with us, and they cancel it, and then they want to reinstate it two months later.”
Those aren’t bad customers to Nitschke’s way of thinking. “It’s a customer that just wants something different. They want a product that you don’t offer today, and they’re solving [their problem] through a really painful process for everyone who’s involved,” he said, explaining that the mindset should have been to do something different for that type of customer.
While Nitschke was building Bunker, Sam Hodges and Travis Hedge were starting to build Vouch, an InsurTech focused on the problems of one very specific set of customers who they felt weren’t being well-served by existing insurance companies. “We saw an opportunity to uniquely build solutions catering to the innovation economy—folks who are building high-growth, technology-forward companies, and also ones in frontier sectors [like life sciences] that traditionally have been harder to insure,” Hodges told Carrier Management in a joint interview with Nitschke last month.
“We believe we can use technology and advanced analytics to build fundamentally better commercial insurance products,” Hodges added, expressing a second basic idea behind Vouch, an InsurTech providing coverages like liability, D&O, E&O, EPL, cyber, fiduciary, crime and property insurance to early-stage to middle-stage technology startups—along with some novel products like “work from anywhere coverage,” which specifically cater to the risk management needs of startup companies. (“Work from anywhere” covers equipment and other property owned by a startup regardless of location.)
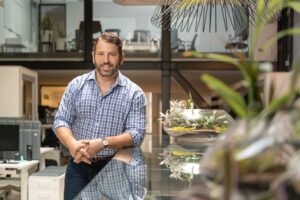 “If you are a startup, it does not matter what type of roof the WeWork space you’re in has. That is not a relevant risk factor.”
Sam Hodges, Vouch
“Very few tech companies own their own buildings,” for example. “If you are a startup, it does not matter what type of roof the WeWork space you’re in has. That is not a relevant risk factor,” Hodges said later in the interview, also explaining how Vouch has used analytics to create an underwriting process that provides most customers with a quote within 10 minutes and a bound policy the next day.
Customers who want to change coverage aren’t bad customers at Vouch, where a technology platform accommodates changes in clients’ exposure bases. “We often do midterm upgrades, or cancel rewrites with higher limits or broader coverage,” Hodges said at another point in the interview.
“We want to build the best insurance policies for companies that are building the future,” Co-Founder Hedge told Carrier Management in a separate phone interview, repeating a mission statement that Hodges shared almost word for word. “We want to be the first insurance policy for every venture-backed company out there, and then really build the unique capabilities to scale with these companies through IPO,” Hedge said.
Even high-growth InsurTech businesses, like Bunker, could be potential customers, Hodges confirmed.
Paths Come Together
Nitschke actually didn’t sign onto the Vouch team because he was scouting out coverage for Bunker. Late last year, Nitschke recognized that Bunker had reached a stage where he felt comfortable stepping aside from the CEO role. (Related article, “An InsurTech Founder Moves On“) While he was taking time off and thinking about what to do next, Nitschke’s wife, the HR director for Hodges’ last venture, Funding Circle, made an introduction.
Funding Circle, a small business loan platform, is one of three companies that Hodges co-founded. “A big part of being a successful entrepreneur, particularly in that tech-forward high-growth space, is really just understanding what are the risks you want to take and what are the risks you want to mitigate,” Hodges said, giving some of the backstory that motivated the creation of Vouch.
Like Nitschke, Hodges had his own frustrations with insurance. Giving the perspective of an entrepreneur that needed to buy insurance multiple times, with buying decisions often prompted by trigger events, such as closing a lease or debt and equity financing deals, or contract requirements related to enterprise sales or partnership agreements, Hodges said that getting insurance always took way longer than he felt it should. “The coverage being recommended or offered wasn’t tailored to need, and it was a very unbundled, very paper-based experience,” he added.
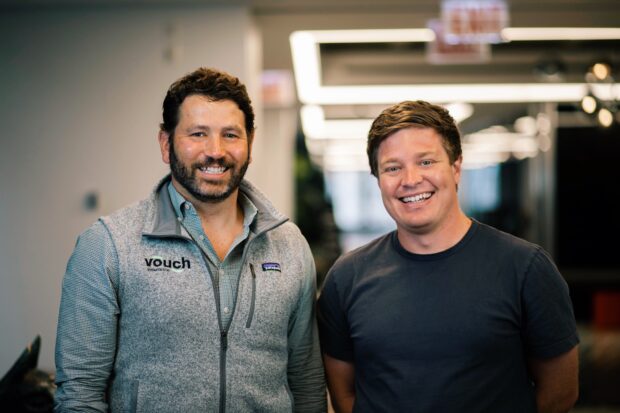
“As an entrepreneur, where you have an expectation that you can use software basically to manage other aspects of your company, insurance honestly just felt like a black hole. It was a real gap,” said Hodges, who earlier in his career was an investor in the first wave of insurance technology companies. (Fun fact: In several video interviews online, Hodges notes that he worked alongside Larry Wilson, the founder of Policy Management Systems.)
Hodges also said that during the moments when he had risk events, he didn’t find the insurers or brokers he had to be particularly helpful. “We were on our own to navigate those risk events,” he said, adding that his experiences weren’t unique. “Across the businesses I’ve been watching for the last 15 years or so, it’s very common to go through things like cyber events, trademark disputes, employee-related disputes, investor-related disputes,” he said. “If you can actually educate entrepreneurs and founders on, No. 1, how do you avoid such things, but also No. 2, what are good practices for dealing with those risk events if and when they come around, that’s not only really good for the company and for the entrepreneur, but it’s also really good for you as the insurance provider,” he said, explaining an education concept that’s also baked into what Hodges and Hedge are trying to do with Vouch.
“I’ve spent a lot of time over the last decade thinking about how to help other entrepreneurs be better entrepreneurs…I’m just a big believer that entrepreneurship and innovation in technology and life sciences can drive real positive change in the world. And, if you can provide tools and services and education to folks who want to build companies, that’s something that’s a purpose worth pursuing,” he said, explaining Vouch’s overall mission to help entrepreneurs navigate risk events.
Hedge, who had been investing in entrepreneurs at SVB Capital, and before that at Nationwide Ventures, had only a brief failed attempt at tech entrepreneurship during his college days. But he grew up in a family of entrepreneurs. His parents built an insurance agency, HR Butler, which like the technology companies Hodges built had a risk event that helped fuel Hedge’s desire to build an operation like Vouch, Hedge recalled during an interview.
His parents’ agency got hacked a few years ago, just a few months into his tenure at SVB. “It got me thinking a lot about [the fact that] whether you’re a tech entrepreneur or a small business, you face a lot of the same risks as a Fortune 500 company. But you’ve got a fraction of the resources to combat that,” he said, noting that his father’s firm, which had one IT person doing laptops, ultimately got things patched up. “It really got me thinking a lot about how you can do things differently.”
Root for Commercial Insurance
Like Hodges, Hedge said he had seen “how manual and broken the process” of buying insurance was for startups when he was working at SVB and at Nationwide, where Hedge helped to build Nationwide Ventures. The two co-founders first met when Hedge worked at SVB and he brought Nationwide’s executive committee to Silicon Valley to introduce them to startups—Hodges’ Funding Circle being one of them. A mutual friend at Ribbit Capital, which ultimately helped to seed Vouch, reconnected the two men with a common vision years later, and after “founder dating” and “whiteboarding the ideas out,” they launched Vouch in 2018, with SVB alongside as an investor and partner.
 “We want to be the first insurance policy for every venture-backed company out there, and then really build the unique capabilities to scale with these companies through IPO.”
Travis Hedge, Vouch
Hedge said another experience led him on the path to co-founding Vouch, recalling how a relationship with Alex Timm, the CEO of Root Insurance, led him to start thinking about creating the counterpart of what Root built in personal lines—a full-stack InsurTech carrier—on the commercial side of the insurance business.
“Six months into the job [at SVB], I was very excited about AR-VR and all the ‘shiny objects,’ out there in technology at the time. But I remembered this insurance thing I spent my whole life around.” (Fun fact: In addition to his parents being insurance agents, Hedge’s grandmother was a senior marketing executive for Nationwide.) “I reached out to the smartest person I’d worked with at Nationwide,” he said, referring to Timm, who had left to start Root Insurance a week earlier. “I was really fortunate to work closely with him to help them get the capital they needed to become a carrier. Eventually [SVB] co-led their Series B with Ribbit and I got to be involved with businesses like Ladder Life and a handful of other [InsurTechs] that were taking this vertically integrated full-stack approach.”
“From 2016 to 2018, I spent a lot of time actually pitching SVB, talking to other founders, looking for a company that was building the direct commercial insurance carrier for the technology industry,” Hedge recalled.
“When I say we want to build the Root for commercial insurance, it’s really on two dimensions. First, I think you’re able to build insurance products—new policies, new underwriting guidelines, etc.—a lot faster when you take a full-stack approach…The second piece was around data and connectivity. While Root uses the sensors on your phone obviously to price your driving ability, we look at all the tools that a modern business uses as very analogous in terms of spinning off new kinds of data exhaust that insurers historically haven’t had access to,” Hedge said.
The tools include payment software and cap table software used by VC-backed businesses. (Editor’s Note: Cap tables list information like the value of equity in each round of investment by founders, investors and other owners, ownership percentages and shares by investor). “A big part of our vision has always been to embed within those platforms and ingest those data,” he said. Embedding will drive a more efficient underwriting process. And over time, Hedge and Hodges think it “can fundamentally lead to new kinds of insurance products.”
Crafting a Better Underwriting Model
Not only has Vouch created new insurance products, like cap table coverage, which covers the cost of disputes over ownership percentages and equity, but in early September, Vouch announced that it was partnering with Brex (all-in-one financial software), Carta (cap table management) and WeWork (shared workspaces) to embed its insurance coverage offering in their platforms. Such partnerships add to existing relationships through which Vouch has been the preferred distribution partner of SVB and Y Combinator since its early days.
The September announcement, which disclosed a $90 million round of funding for Vouch from Redpoint Ventures, Silicon Valley Bank Capital, Ribbit Capital, Allegis Group, Sound Ventures and SiriusPoint, also revealed that Vouch has set up its own carrier, authorized to write reinsurance. In conjunction with raising its own Series C round, Vouch also announced that it expanded its underwriting appetite from seed to Series C companies—now delivering insurance to not just early-stage tech companies but also serving the insurance and risk management needs of older growth-stage companies.
“Our current appetite is high-growth, innovative companies—all the way from two people in the garage to [companies] getting ready to think about going public. It’s a very wide swath of the private innovation economy,” Hodges said.
“One of the unique things about serving startups is that they’re very dynamic,” Hodges said. “We have many examples of startups where, inside the time that we’ve been their insurance company, have gone from zero to hundreds of employees, zero to 10s of millions in revenue, zero to hundreds of millions of dollars in financing. That pace of change, and ultimately the scale you can get to quickly in some of these sectors, is one of the things that makes the job of being an insurance provider challenging,” he said, going on to describe one of Vouch’s differentiators—the ability to speed the underwriting process, using a taxonomy of 70 or 80 proprietary risk profiles for target customers.
 The rating classes of traditional insurers and brokers don’t work “in the context of modern digitally native businesses,” Hodges explained. “Most carriers or brokers wouldn’t use separate class codes for a digital health company on the one hand versus a digital gaming company on the other.” But the reality is that a digital health company has wildly different exposures, particularly as relates to cyber and E&O, compared to a digital gaming company.
“The first thing we did was put together a much more nuanced, comprehensive class framework that allows us to call out those distinguishing characteristics and ensure that the coverage we are recommending, as well as the framework we’re using for underwriting and rating, takes those differences into account. And then, on an ongoing basis, we’re pulling in tons of data that allow us to track, in near real-time, changes in how these companies are evolving, so that we can ensure they have the right level of coverage with the right limits, priced and underwritten the right way,” he said.
Hodges contrasted the 70-plus classes to a handful used by traditional carriers. For traditional carriers, classes are: on-premise software, custom software development, electric vehicle manufacturing, “and then everything else that you’d think of as a software or Internet native business” lumped into two remaining class codes. “That is just a very 1992 way of thinking about what technology is,” Hodges observed.
Without tons of actuarial history to fall back on, Hodges explained that the experience of a commercial insurance team with actuarial, underwriting, product development and claims expertise, together with the experience of Vouch’s advisers, is baked into its initial rate filings and underwriting guidelines. (Editor’s Note: Cynthia Powell, former chief risk officer of State Auto Insurance and chief financial officer of Root, Robert Byler, former CEO of Schinnerer Group (now Victor), and Mark Herman, former president and COO of CNA Specialty, are members of Vouch’s board.)
“Honestly, a lot of this is just good old-fashioned common sense,” he said, referring to the process of “hybridizing concepts that already exist in the traditional market” to understand the risks of a digital health company—some of which are inherent to being an Internet company, and other risks that are inherent to being in a particular category of health services.
A Reinsurer Is Born
Vouch has also leveraged insights from its reinsurance partners along the way, Hodges said, later noting that Munich Re, an early reinsurance partner, no longer participates on policies that Vouch writes on State National paper. “Because our new program includes discretion, that’s not something that the Digital Partners [unit] of Munich Re can support,” he said, explaining that before July of this year, the vast majority of Vouch’s business was being auto-decisioned. Now that Vouch is writing more mature, complex growth-market accounts, Vouch needed to introduce underwriter discretion—a different approach than the one Munich Re Digital Partners historically would have supported.
There are now four reinsurers backstopping the programs: SiriusPoint, Greenlight Re, ISMIE—and, importantly, Vouch Insurance Company. Previously operated as an MGU, Vouch now participates materially in sharing the risk as a reinsurer, moving the InsurTech closer to Hedge’s vision of creating a full-stack carrier.
“In general, our philosophy is we do want to take as much risk as possible on our balance sheet while being mindful of how to scale the business in a capital-efficient manner and share the risk appropriately,” Hedge told Carrier Management. “By no means is it just a token, ‘Oh, we want to have a little skin in the game. Give us 5 or 10 percent. It’s a much more material number than that,” he said.
“When we set out to start the business, my bias was I wanted to be a carrier as soon as possible so we can have that control over underwriting, etc. But our business is very different from Root’s. There, you’re talking about a monoline personal lines business where capital requirements are roughly a tenth of what they are to build an A-rated carrier in our category.” Hedge also noted that half of Vouch’s client base sits in California and New York, states that have three-plus-year seasoning requirements.
Does Vouch aim to become a primary carrier in the future?
“We’re very focused on building out future programs with our current partners and continuing to build out the balance sheet for the Vouch Insurance Company, which I foresee operating as a reinsurer for a long time to come,” Hedge said.
While setting up Vouch Specialty is another step into the future, the executives are keeping specifics about the unit Nitschke is heading up under wraps for now, only revealing that it may involve bespoke offerings for later-stage startups with complex insurance needs to fill in gaps where Vouch’s current selection of proprietary policies aren’t quite enough.
During the interviews, Hedge also offered insights for other InsurTech leaders about the process of becoming an authorized reinsurer in the state of Illinois. And he and Hodges shared more insights about insurance distribution and the unique risks of Vouch’s client base. Details are available in related articles exclusively on CarrierManagement.com:
 Despite Increasing Threat, Users Keep Same Password Combos
 Grand Theft Auto VI Frenzy Highlights Digital Infrastructure Insurance Risks
 California’s Kim Says Insurance Should Fund Wildfire Safety, Not Super Bowl Ads
 Binance $6.3B Theft Prompts Closer Scrutiny by Insurers