

Back in 2015, Douglas Ver Mulm was co-founder of Vervoer Rideshare Fleet, which runs and manages rideshare vehicles in New York City—a side gig when he was a lawyer at Mercer handling data security and technology initiatives. That’s when the idea for Stable Insurance was born.
The fleet would rent out cars on a weekly basis to Uber and Lyft drivers (who didn’t use cars they owned), and the commercial auto insurance necessary to operate in New York City was costly and didn’t function well, Ver Mulm said in response to a series of email questions from Carrier Management.
To make things easier, Ver Mulm worked with a business partner (a data scientist) to build a platform that collected telematics data from the rideshare activity taking place. The idea was to find a better way to match the commercial auto premium with actual risks the fleet was taking. By 2017, he quit his job at Mercer and began a focus on developing the startup from that platform idea, which became Stable Insurance. (Ver Mulm is still a board member of the rideshare company he founded.)
Stable Insurance now handles multiple rideshare policies, and the managing general agency is exploring expansion into other commercial and hybrid commercial coverage, including delivery and part-time rideshare insurance.
For now, Stable is based in a WeWorks Labs accelerator program in Dumbo, Brooklyn in New York City, where the company has focused on getting licensed and learning the basics about commercial auto insurance and rideshare insurance regulations. It is part of the InsurTech NY collective.
Stable Insurance now employs seven full-time people, up from four in June, and is spread out between Hartford, Conn., New York City, Philadelphia, South Dakota and California.
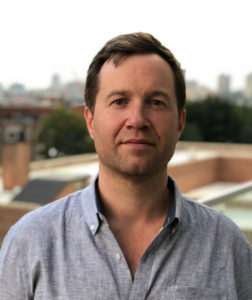 Being an early-stage [company] means we can be much more insurgent-like. We can pivot quickly if need be…We are the only group of people we need to prove ourselves to.
The company uses Slack, Zoom and Monday to stay linked together and plot its growth. In the near future, its headquarters may move to Hartford in order to tap into the region’s insurance talent. (Other parts of the company would remain remote.)
Beyond Ver Mulm, Stable’s founders include Stephen Dekker, a data and analytics expert, and John Salvucci, a broker and insurance industry veteran who was initially an adviser of the company before becoming a co-founder.
Below, Ver Mulm addresses some of the growth challenges and opportunities Stable Insurance has faced so far. He also describes the company’s business plan in detail.
Q: What does Stable Insurance do?
Ver Mulm: Stable offers commercial insurance that drivers need to conduct rideshare operations. We’ve digitized and streamlined the product distribution and administration so that drivers can purchase insurance quickly and interact with it day or night on their time.
We’ve also been developing a usage-based commercial auto insurance product for fleets that have seen dramatic drops in their vehicle utilization. Our platform can plug into any third-party data source (any telematics firm offering up an API, for instance). So, we quickly built that product. We are now discussing this with reinsurers. The demand for this product is high.
Stable’s platform has garnered interest from carriers handling other commercial auto insurance types and from brokers looking to automate their processes. It is likely that after we establish ourselves further in the rideshare space, we may branch out into those new product areas.
Q: How much financing have you raised to date?
Ver Mulm: We’ve raised $250,000 in angel and accelerator grant funding. Otherwise, we’ve been bootstrapped from founder funds and, more recently, income from operations.
Q: What are your biggest concerns when your startup is super early stage, with like two or three people involved?
Ver Mulm: Other than how are we going to pay ourselves, we don’t have many concerns. When you’re small, you can take significant risks. You don’t have a massive team to support, you don’t have enormous expectations to fill, and you can continue to work quietly in the background.
Early on, we were somewhat frustrated that other startups with less advanced products—but established books of insurance business from related broker operations—were able to convince a reinsurer to offer them capacity; were able to get capacity to write a product and raise money. In hindsight, now that COVID has hit, we wouldn’t want to be in their shoes. They have large teams they need to continue to pay and expectations from the market and their investors that will be impossible to meet, given what has happened to commercial auto insurance.
Being an early stage [company] means we can be much more insurgent-like. We can pivot quickly if need be. We have a small team and haven’t stretched ourselves too thin, and at present, we are the only group of people we need to prove ourselves to.
Q: How do you move a startup from that infant stage to the immediate next level up? How do you figure out those logistics—on your own, or do you turn to outside consultants?
Ver Mulm: We don’t think there is a set way, nor would we rely on a consultant to help here. One of the best things we did early on was to get very involved in the NYC startup community. Anytime we have a question, we have an abundance of mentors to lean on. That right there might be the answer to how to move from the infant stage.
Surround yourselves with people smarter than you and that have done this before. Your situation is always going to be different, but having those people as a sounding board will prove invaluable and help de-risk any decision you make while trying to handle that transition.
We will say, making that transition during COVID and while working remotely has probably made the work harder. It’s harder to coalesce and develop rhythm while everyone is remote. That said, we have some of the best people working for us, and so we feel confident it will only make us stronger. When we finally can all start working together again, it should speed up any efforts at that point.
Q: What is the easiest thing about creating a company from scratch?
Ver Mulm: The fact that you have no systems or processes in place. You can build everything—from the technology to the operations to the culture—fit to purpose of the goals you are trying to achieve. This is in contrast to incumbent competitors, who have a massive amount of technical debt and carry over processes to deal with. There are also not politics to deal with. Decisions get made and are executed in real time—no committees, no red tape, no boss to make look good.
Q: What is the hardest thing about creating a company from scratch?
Ver Mulm: The fact that you have no systems or processes in place. A true double-edged sword. While that does give you a massive amount of autonomy to create, it can also lead to days where you just want someone to tell you what the best way forward is. Even if you are good at making decisions, the sheer number you have to make to continue moving forward means you will make some bad ones. And fixing those decisions can take a lot of time later on.
Q: In your company’s earliest stage, what was the biggest mistake you made?
Ver Mulm: Early on, we assumed the best product and technology was all we needed to get deals down with insurers. We were very wrong. Insurers are the most risk-averse people in the world. Novel ideas and fancy technology scare them. They want data and a lot of it to back up what you are doing. They are not interested in testing for the sake of testing, which is basically what a startup does during the early stage of its existence. We quickly learned how to massage what we were saying to not spook the capacity people.
Q: In your company’s earliest stage, what was the most effective decision you made?
Ver Mulm: After making the realization above, we knew we needed to get an “insurance adult” in the room with us. We were able to convince one of our advisers, John [Salvucci, a veteran of AIG, among other places] to join us full time as a co-founder. He’s now on every current and potential insurance partner call with us, making sure we don’t spook the capacity people.
 Workers’ Compensation’s Real Challenge: Orchestration
 Xceedance Says for Insurers, AI Advantage Is in Orchestration
 AM Best: Social Inflation Drives Surge in Commercial Auto Liability Claims
 Viewpoint: Insurers Are Automating the Front Office While Ignoring the Function That Determines Trust