
Less “gotcha.”
More “we got you.”
Whether it’s the new website banner, a chorus dressed in light pink singing a jingle on TV commercials, or popups in the middle of articles about insurance (I get a lot of those), the message from Farmers Insurance is clear: Clarity is the idea.
Executive Summary
“Farmers Coverage on a Page” and Farmers Coverage Review sessions are two features of a refreshed approach at Farmers aimed at delivering more transparent insurance experiences to customers. Here, Christine Buxton, senior vice president and head of service transformation, a 23-year veteran of the company, explains how clearer communications—delivered by Farmers agents, in direct-to-customer materials and during moments of claims—build customer trust in the carrier.Christine Buxton, vice president and head of service transformation at Farmers, didn’t use the term “gotcha” during a recent interview for Carrier Management’s series on trust in the property/casualty insurance industry. Instead, she observed, “Insurance does have a reputation for fine print, for being confusing,” offering an aspect of the industry that erodes trust and describing a core building block of an ongoing service transformation at Farmers aimed at bolstering it instead.
When Farmers unveiled its “more modern, distinctive brand experience” in mid-July, key customer experience initiatives aimed at decoding the fine print included “Farmers Coverage on a Page,” described as “a snapshot of coverage included in select Farmers auto and home policies,” and the availability of Farmers Coverage Review sessions, which allow customers to have simple conversations with Farmers representatives to “discuss current coverage and help them identify opportunities to change their coverage, save money, or both.”
Related article: Farmers Making It Easier for Consumers to Understand Insurance
“Establishing trust with customers in our industry is an ongoing challenge, but it’s one that we really focus on and take seriously,” Buxton said during a mid-August interview.
Farmers, she said, is focused on being transparent and on making things easy and understandable in all types of interactions—both customer-facing and behind the scenes. “Those are really levers that we use to establish trust in a challenging industry,” she said. “It’s ingrained in everything we do,” she said, highlighting the claims process, the sales process and other service interactions.
First, “we let customers choose what type of relationship they want to have with us, and then we establish trust within that channel,” she said, later confirming that the exclusive agency channel remains the biggest one at Farmers. “That choice of showing up for the customers, regardless of how they want to interact with us, becomes a trust signal in itself,” she said.
“A lot of customers still prefer an agent in their local community.” They like to be able to go into an office and speak with someone who helps them understand insurance and what they’re buying. But as customer preferences shift, and more come into the Farmers direct channel, making investments in customer-facing digital and self-service tools are a key part of the picture, she reported. “We’re making things simple for them even if they don’t have an agent or someone to help them.”
Offering a specific example of how Farmers is working to demystify insurance for customers on the agency side, Buxton pointed to a premium change comparison tool available to agents and customer service reps. The AI-fueled premium comparison tool, she said, “quickly goes and collects needed information about why a customer’s price may have changed at renewal. There are so many different factors—complicated factors around rating and chargeable claims,” she said. The tool provides the why behind a premium change “in simple terms,” she said, suggesting that cutting through the complexity for agent and customer alike allows for a more meaningful discussion. “That, again, helps us establish trust,” Buxton asserted.
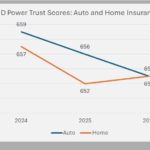
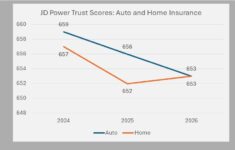
Several recent JD Power studies demonstrate the impact of transparent pricing on customer trust. According to the JD Power 2024 U.S. Auto Insurance Study, for example, the average trust score among customers who experienced insurer-initiated price increases—but who expected the increases and fully understood the reasons for them—was nearly identical to average trust score for customers with rate decreases (just one point lower).
In JD Power’s 2025 Insurance Customer Retention Playbook, the consumer insights and advisory firm noted that scores for the trust dimension of overall satisfaction scores jump 30% when customers understand the reasons for price increases through education processes designed around clear explanations and tools to compare coverage scenarios.
(Editor’s Note: Since 2024, trust has been the most important dimension of JD Power’s annual customer satisfaction indices calculated for U.S. auto and home insurers. Read more about JD Powers take on the customer trust in the related article, “Help Me Understand: How Insurers Build Trust.”)
At Farmers, the premium change tool was borne out of agent frustration. Buxton said she and her team meet with a panel of agents almost weekly. “I remember actually hearing from our panel, ‘In order for us to figure out what made a premium increase at renewal, you almost need like a PhD. We’re going between all these systems, all these screens.'”
“It makes it really hard to explain it to the customer because they said they as agents weren’t equipped with a simple explanation themselves.”
She continued: “The technology has evolved enough. We can leverage AI tools to go out and seek and pull all of this information together for the agent. So, they’re spending less time doing the research and going between different systems. They have something packaged up that makes that explanation easier. And that just makes the discussion between them and the customer better,” she said.
Most agents have that tool in hand today, while Farmers will roll the tool out to agents in remaining states this month, Buxton noted.
She also confirmed that at Farmers, the premium change comparison is meant to be a proactive tool used by agents rather than one they just have at their fingertips when customers question premium jumps. It’s intended for the agent saying, “I saw your premium changed and here’s why,” she said, highlighting the idea that making things easy also means staying one step ahead. “The agent does have that information early so that they can reach out and have a discussion with the customer before the customer actually sees their renewal packet that may show a price increase.”
Making sure agents are “better equipped to have transparent, meaningful discussions with their customers” has been a major focus for Buxton and her team for several years. “Sixty-plus efforts,” she reported, have targeted ways to allow agents to spend less time trying to collect data and more time on customer relationships.
“AI doesn’t establish trust right now, right? Our humans do. Relationships do.”
Christine Buxton, Farmers
Buxton flagged Farmers Coverage Review as another example of a tool with which Farmers is helping agents to be proactive. “This is something we’re still putting the final touches on,” she reported, also noting that the agent outreach doesn’t have to occur at renewal. “It can be at any point in the customer journey. The agent can reach out and say, ‘You’ve been with us for a while. We haven’t gone through your coverage. Let’s take a look at it together,” she said, explaining that the tool pulls important pieces of information about the customer and what coverages the agent and customers may need to talk about.
“Do they have a new driver coming up? Just some of these life-changing events. And the tool enables agents to see that ahead of time and then be proactive and reach out to the customers,” she said. “We’ve seen that agents who are proactive like this and reach out first really establish more trust with the customer. Those customers stay with us longer,” Buxton reported.
As for the progress of the rollout, Buxton said agents do have a coverage review option today, “but it’s not as advanced as we are working to make it,” adding that the full release of the AI-driven coverage review tool will happen in the fourth quarter. A new option is also available for people who aren’t our customers. They too can go to the Farmers website and request a review of their current coverage, Buxton said.
The website page coaches customers through the steps of setting up an appointment and gathering information for the session with an agent or a representative: “Ideally, we need to review the summary page from your insurance policy. Most insurance companies make policy documents available through their website or mobile app. A typical path to find these documents is: My Account → My Policy → View Policy Documents. If you see a page called “Declarations,” you’re getting warm,” the website explains, going on to list individual pieces of information on the dec page and translating “lawyer-y jargon.”
Farmers chooses to translate terms like “coverages,” defining this as “buckets of protection in your policy, like personal belongings, living expenses while your home is being repaired, etc.” And “coverage limit” is explained as “the ceiling (or ‘up to this much max’) for each bucket of protection.”
“That choice of showing up for the customers, regardless of how they want to interact with us, becomes a trust signal in itself.”
The goal of the session is to identify whether Farmers has something comparable—or better options. “What does that look like? What does that look like in terms of price?” Buxton asked. Noting the similarity to coverage reviews for existing customers, she said, “We take the time, we really talk in plain language about what coverage they have, so they feel like they have a good understanding of the product.”
Recognizing that affordability is a key customer concern, Carrier Management asked whether coverage reviews are mainly aimed at lowering or eliminating some coverages and about how Farmers balances discussions about lowering premiums against the potential to exacerbate trust problems if eventual claims ultimately fall outside of narrower coverage terms.
“I’d say those are customer-led discussions,” Buxton said. “There are different scenarios where maybe a customer that’s more price-sensitive is seeking options that maybe would make the premium go down through a higher deductible or whatever options are out there. But then there are customers who maybe have been with us for a while, maybe they have a home and an auto, and they need an umbrella policy… They’re building their life as they are customers with us. And some life events may mean that they’re seeking more coverage.”
“We try to be value-driven but give different options that may suit [each] particular customer.”
Coverage on a Page
Simplifying coverage while not opening the door to future coverage litigation is another balancing act that carriers have dealt with in the past, as evidenced by the critical reactions of coverage analysts to Lemonade’s simplified “Policy 2.0″ in 2018 and the three-page small business insurance policy that was the centerpiece of Berkshire’s THREE in 2019.
Related articles: I Kind of Like Policy 2.0; Berkshire Hathaway Direct: ‘Challenging the Normal’ With Three Pages
Buxton clarified that Farmers “Coverage on a Page” does not replace the traditional policy packet delivered by Farmers to home and auto policyholders. “What it does is it tries to give kind of a simple summary of all the fine print that is in there so that the customer has a better starting point.”
Luis Sahagun, director of external communications for Farmers, noted that the “Coverage on a Page” summary shows up early in the multi-page policy booklet, which still governs the relationship. A unique feature of the one-page summary is that it lists some things that may not be covered but could be optional endorsements, he added.
On sample pages shared by Sahagun, for example, easy-to-spot light blue textboxes flag the fact that flood is an optional and “highly recommended” coverage, also listing cyber and identity shield, equipment breakdown, home sharing, and water backup and sump overflow as potential optional coverages for the particular homeowner whose policy is summarized. “Never covered” are items like “routine wear and tear, deterioration, maintenance issues,” another clearly labeled text box calls out, with “flooding and surface water” also on that second list.
Unlike the legal text-heavy documents that policyholders are used to sticking in a drawer, the one-page summary features an illustration of a house at the top—presented in the light pink and blue hues that now identify the Farmers brand—with coverage details superimposed on sections of the image. “Dwelling, Coverage A—Covers the cost to repair or rebuild your home,” the first description says next to a line ending at the edge of the roof. “Personal property, Coverage C—Covers repair and replacement of our belongings,” the second says, pointing to an inset image of a pink TV and objects on a shelf.
Prominent pink textboxes highlight the premium amount and itemize various discounts, while a separate list delineates deductible amounts for wind and hail, tropical cyclone, and all other perils.
The page is not completely clear of any fine print, however. Smaller type at the very bottom of the page says, “It is your responsibility to select your coverages and limits… This document is a summary and the information in this document does not replace or change any policy provision… In the event of a conflict between the policy and the summary, your policy provisions shall prevail.”
Still, the page is mostly user friendly. “To me, [it’s] a refreshingly transparent way to show a customer what they have and don’t have,” said Buxton. “When you are clear, and they’re able to understand in simple language what they’re purchasing and what is not included, that goes a long way in establishing trust.”
What About Claims?
Buxton said similar themes carry to the claims process at Farmers. “It’s one of the most important relationship-building times”—often being the only touchpoint after a customer purchases a policy and pays the bills. “So, we really make sure we are being proactive in terms of explaining what they can expect, providing proactive status on who their adjuster is, when they can expect to be contacted. And then we’re taking the time to explain the process [and] also the coverage.” Essentially, Farmers is “trying to make things easy, transparent again. Not being vague; being proactive. Those are just things that are ingrained in our process,” stated Buxton, whose career at Farmers started in claims roles.
“We’ve invested a lot of time, resources and money into making sure we are an organization that can be first there for customers when they have a catastrophic experience,” she added. “There’s no delay. We’re there when they feel the most vulnerable,” she said, noting that through her own on-site visits during catastrophes, she has seen the impact on customers first-hand. “We’ve earned lifelong customers because of how we show up when they need us the most.”
“That’s where customers feel the value of the product… So, we make sure that we are showing up in a way that inspires confidence, establishes trust. We’re taking our time, being transparent, cutting through insurance lingo, and just making sure that they have an understanding of the product and how we’re showing up for that.”
Human at the Helm
While Buxton mentioned the use of AI during the early part of the interview, when asked about the potential of AI to erode trust, she explained that, at Farmers, humans use AI to make them better at their jobs. “AI is a tool that our agents, that our reps, our humans use… It’s not replacing what they do because AI doesn’t establish trust right now, right?”
“Our humans do. Relationships do,” she said, referring to the way the premium change comparison tool, for example, cuts through the complexity of the insurer’s systems and all of its data to pull together the information an agent or rep needs to have better, more transparent conversations with customers.
Agreeing that trust in an organization starts with leadership, Buxton said Farmers leadership establishes trust within the organization by “being clear and believing in the message that we’re putting out there.”
“So, if we’re saying, ‘Be proactive. Be customer-centric. Meet the customers where they are,'” then that means leaders must be “truly backing that up. And I really think we have that at Farmers, from our CEO down, the strong belief that being clear, building relationships, providing different options to customers is what makes us successful as a business.”
“We walk the walk when we talk the talk… I do think from the CEO down that that’s part of our culture,” she said.
*Top photo Adobe Stock image (Lubo Ivanko) edited with AI
 Future Cyber Catastrophe Events May Be Different, Yet Not Unknown
 Insurity Announces Ratio Content and Rating Engine
 Viewpoint: What U.S. Insurers Should Learn From the EU AI Act
 Nearly 100% Chance of a Mediterranean Tsunami Within Next 30 Years